$31 million was sitting in contracts nobody had reread

I was in NYC this past weekend with a friend. Neither of us are 'shoppers' so we lined up a bunch of IRL 'experiences' - the perfect antidote to an increasingly online world.
Here's what we did, ranked in descending order of 'would do again':
- The Stand Comedy Club - unwittingly placed in the front row, only slightly roasted, really funny and such excellent value for money at $30 for 90 mins of fun.
- New York Rangers - ice hockey at the world-famous Madison Square Garden. Incredible athletes and a great atmosphere helped a lot by the 6-2 home team win.
- Blue Note Jazz Club - really chilled out experience with incredible talent on display. Show started an hour later than advertised so we both ended up nodding off.
- NY Comic Con - This was both expensive and outrageously busy. Impossible to browse the stalls, nearly impossible not to contract a bug.
Continuing the IRL NYC theme, I'm appearing on a data/AI panel at the Opus Connect PE Healthcare conference on November 4th and 5th. There's a great lineup of sessions and so many networking opportunities.
I have free ticket codes avaliable for sponsors and capital providers - let me know if you want to come along!
Enjoy the rest of the memo!
Three Things I Learned This Week
The contract says one number and the invoice says another
This week's PE Data Guy guest, Carson Marr, spent years at RSM as one of the people Blackstone called when it bought a company and wanted to know what the technology stack was and what to do with it next.
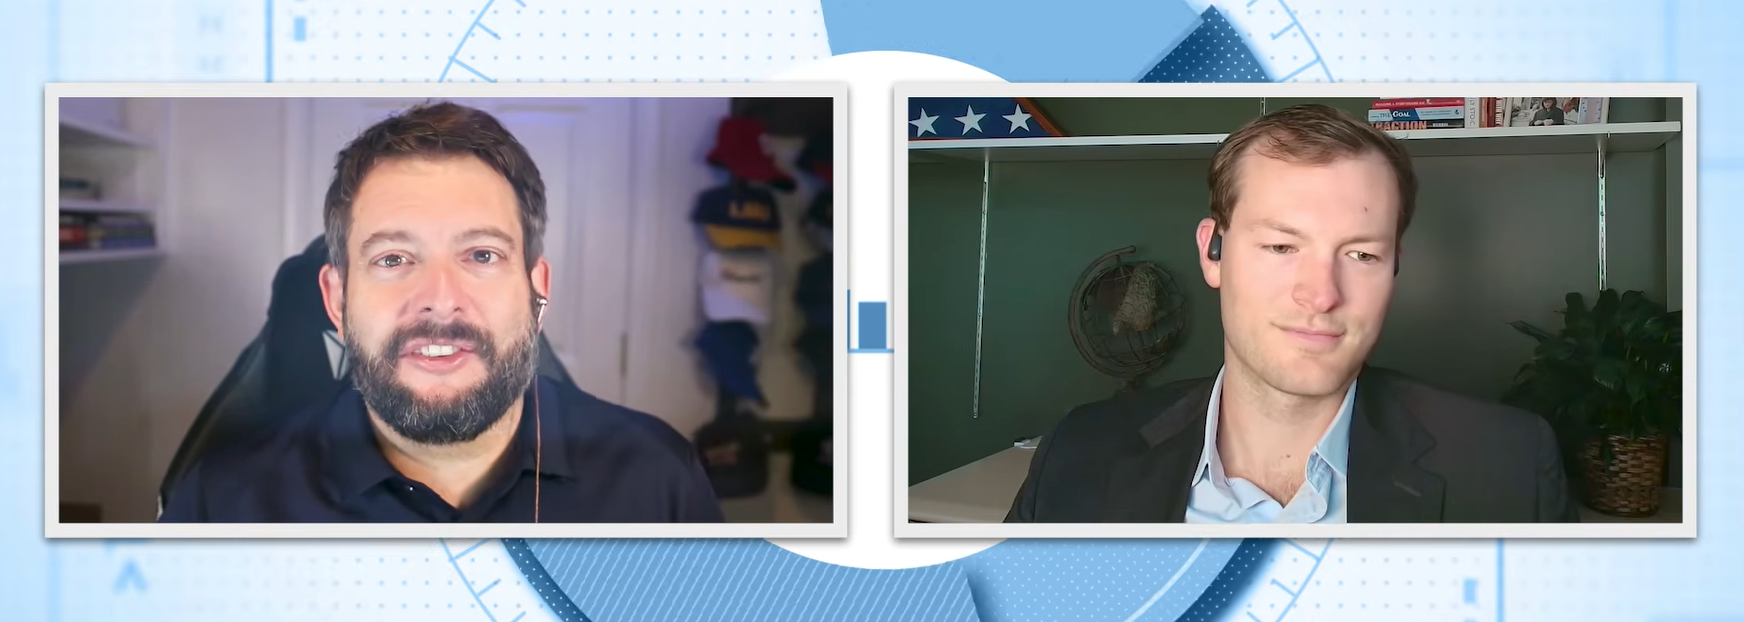
He got tired of deals built on access, where you pay for a team or a licence and maybe a result shows up a year later. So he built Buyable, which only gets paid when a named outcome does.
The find I asked him about was bigger than the version I had heard. The company was $1.2 billion in revenue. His team read every customer contract in 60 days, checked each one against what the billing system was charging, and collected the difference. $31 million.
Where does money like that go? He walked me through it. Picture a $50 million business with a controller and a few directors of finance. A deal gets signed and 50 pages of paper land on a desk. A human reads it and types what they understood into the billing system.
Do that a hundred times a week and something gets missed. Then that company gets bought in a roll-up and merged on a deadline across several billing systems, and something gets dropped.
His example was a 3% escalator, or CPI, that is meant to fire every January. Year one it fires. Year two the company adds a meter to how it bills that customer, and the CPI never fires on the meter.
The base rate steps up on schedule, the meter does not, and nobody can see it without going back to the original paper and doing the maths. Then the controller who typed it in leaves during the acquisition, and the contract sits in a data room nobody has opened in three years.
“These are not massive sums of money on the individual case,” he said. Across a portfolio they are.
The part I keep thinking about was his read on why executives buy the way they do. At a billion dollars of revenue the downside of a bad choice is bigger than the upside of a good one, so you need a CRM and you take Salesforce, because how else are you going to go.
Carson’s point is that the same executive is graded at the board. “We put a CRM in place and we bought ZoomInfo and our sales grew 3%. Did I contribute to that?” is a hard story to tell. A partner who looked at one specific area and brought in an extra 31 million is a story they can stand on.
One line from the episode I have already stolen. Carson’s former CEO used to say that automation lets you do things faster, but if you are still doing the wrong thing, you are only doing the wrong things faster. Simplify first. Then automate.
One thing to take into your next board pack review. The gap between contract and invoice cuts both ways. Found two years before a sale, it is revenue you keep and EBITDA you get paid a multiple on.
Found by a buyer’s diligence team, it is a reason to re-trade. Pull ten contracts with escalators and check this year’s invoices against the paper. If they tie out you have lost an hour. If they do not, you have found where to look.
Watch the full conversation here
The premium for being good is down to 5 percent
GF Data tracks completed private equity deals in the middle market. Its first-half read, presented at Middle Market Growth’s October webinar, has 170 deals done, a pace of about 340 for the year, roughly 10% more than 2025. The average price was 7.1x trailing EBITDA, within a tenth of a turn of both 2024 and 2025.
The number that matters sits underneath the average. Historically, buyers paid about 15% more for a business that cleared GF Data’s bar for above-average financial performance. That premium was 7% in the first quarter and 5% for the half.
Two things are squeezing it from either side. Constrained revenue growth is pulling down what buyers will pay for the strong performers. Competition for ordinary add-ons is pushing up what they pay for everyone else. Business services led at 7.5x. Distribution fell to 6.0x, its weakest reading in the series.
I read it this way. Nobody is paying for a reputation any more. If the premium for being good is five points, the only way to earn more than the market is to show the growth in numbers a buyer can rebuild without you in the room.
Read the GF Data summary here.
The buyer at the end of your hold is probably a corporate
PitchBook’s third-quarter Global M&A Report puts a number on something I have been hearing in rooms all year. Private equity buyers paid a median 11.5x EBITDA in the quarter. Strategic buyers paid 8.9x. That gap of 2.6 turns is the narrowest since 2023.
The reason is not that corporates got generous - leverage got expensive. A sponsor’s bid is built on debt that costs more than it did, and a cash-rich corporate can pay in equity and wait. So buyouts fell to 31.8% of all M&A value, from 41.6% last year.
What that means for a company mid-hold is simple to say and hard to live. The buyer you are preparing for is more likely to be a corporate with an integration team than a fund with a deal team.
A deal team asks whether the numbers support the model. An integration team asks where the numbers come from and how the systems plug into theirs, because on day one they have to run the thing.
Carson’s roll-up, four billing systems merged on a deadline and a contract nobody has reread since, is what that team finds in the first week.
TA Associates sold Rocscience to Hexagon this month for $535 million. That is the shape of it. The exit was real, and the buyer was a corporate.
Read PitchBook’s note here.
Two News Stories From This Week in Mid-Market PE and Data
Exits came back, at the top of the market
Sources: AltAssets, Oct 8 and Oct 12 | Alternatives Watch, Oct 8 and Oct 9
What happened.
AltAssets’ read of the quarter has global private equity exit value up 65%, with the recovery concentrated in the largest deals, while fundraising keeps shrinking. The tape backs it up. Sycamore sold Boots to the Weston family for $8.9 billion. GTCR closed its fifteenth flagship at $14.2 billion, almost a quarter larger than the one before.
Rob Wolfson, who ran healthcare at H.I.G., raised $1.05 billion for a debut fund at Aphias. Consonance closed its third healthcare fund at $1.35 billion, 58% larger than its last, oversubscribed in under four months.
Why you should care.
Money is moving again where the assets are large and the stories are clean. For a mid-market company three or four years into its hold, the exit window has not opened the same way, and the sponsor that just raised a bigger fund is under more pressure to show distributions from the old one. The company that gets sold first is the one whose numbers do not need explaining.
Continuation vehicles are becoming a way of life
Sources: Shumaker client alert, Oct 5 | Private Funds CFO, Oct 7 | PitchBook, Oct 13
What happened.
Secondary transactions hit $240 billion in 2025, up 48%, and Jefferies expects them to approach $300 billion a year within two years. Closed continuation vehicle volume rose 34% in North America. There is now a name for rolling an asset from one continuation vehicle into another run by the same sponsor, the “CV squared,” which Raymond James says could turn “a one-time liquidity solution into a repeatable ownership model.”
Only 14 PE-backed companies went public in the first quarter, down from 29 a year earlier. This week the Teacher Retirement System of Texas sold a $1 billion private equity portfolio to Coller and EQT.
Why you should care.
If your sponsor rolls you into a continuation vehicle, you are not avoiding a sale. You are getting a second set of buyers, the new investors in the vehicle, who ask their own valuation questions and are demanding more disclosure on conflicts and marks than ever. The numbers have to hold up twice.
In 37% of last year’s continuation funds the sponsor invested alongside its newest flagship, which means the people who priced you the first time are pricing you again, with their own money in it.
Free Tool of the Week - The Red Flag Audit
Five yes-or-no questions a buyer’s diligence team asks in week one. Can your team reproduce last quarter’s reported revenue from source systems in under an hour? Do finance, sales and operations report the same number for the same metric?
You answer on the page and your score and your first flag come up before anyone asks for an email. Each NO carries the discount a buyer tends to take for it. If Carson’s piece made you wonder what else is sitting between your contracts and your invoices, the first question is where to start.
Two minutes. Take it here
Sign-off
If any of this lands and there is something you think we can help with, just reply. We read everything that comes through.
As always, forward this on to your favorite PE-backed friend.
Cheers,
Graeme